
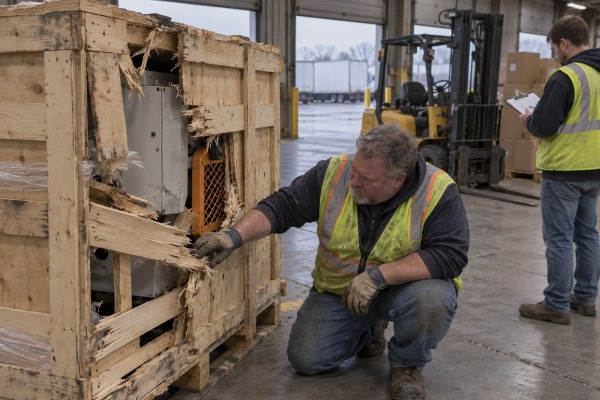
Shipping insurance coverage for a fully automatic pipe cutting machine sounds simple until a crate from our factory arrives crushed. Buyers assume the forwarder’s policy covers them. It usually doesn’t.
Shipping insurance coverage is sufficient for a fully automatic pipe cutting machine only when it is a full-value, all-risk cargo policy covering the complete route, with documented packaging, acceptable deductibles, and clear claim conditions. Carrier liability alone or a forwarder’s generic policy is almost never enough.
The word “insured” tells you nothing about the amount, the route, or the exclusions. So I will walk through what to check, how to value the machine, what policies leave out, and how to file a claim that actually gets paid.
A procurement manager in the US once asked me whether his forwarder’s “insured” note on the quote was enough. I asked him five questions. He could not answer one of them.
You need all-risk cargo insurance written on Institute Cargo Clauses (A), insured at full replacement value, covering warehouse-to-warehouse including loading, unloading, and transshipment, with you named as beneficiary. Then verify the insured amount, coverage scope, route, exclusions, and claim conditions yourself.

Those five questions are the heart of this section. Before I explain them, you need to understand why the default protection on most shipments is so thin.
A fully automatic pipe cutting machine is not ordinary freight. The unit we ship has a powder-coated steel cabinet, a hydraulic cylinder 1, a linear rail, a servo motor, a PLC, and a touchscreen HMI. The value sits in the precision parts, not in the steel. Carrier liability 2 limits ignore that. They pay by weight.
| Protection type | How payout is calculated | What you must prove | Typical gap on a $150,000 machine |
|---|---|---|---|
| Carrier liability under the bill of lading | Weight-based, often around $0.50 per pound | Carrier negligence; “Acts of God” and concealed damage are often denied | Frequently under 5% of replacement value |
| Forwarder’s generic freight or parcel cover | Declared value, often capped per shipment | Varies; caps and exclusions buried in terms | Caps may sit well below machine value |
| Dedicated all-risk cargo insurance (ICC A) | Agreed or insured value | Fortuitous physical loss or damage during insured transit | Exclusions still apply, but value matches the machine |
Run the math once and you will never rely on carrier liability again. Suppose the machine weighs 3,000 pounds. At $0.50 per pound, the carrier owes $1,500. That is 1% of a $150,000 machine. You would also have to prove the carrier was negligent.
In our experience exporting to the US, Germany, Japan, and Mexico, the forwarder “buying insurance” is the beginning of the conversation, not the end. I ask buyers to check five things themselves:
Do not just look at whether the forwarder purchased insurance. Look at what that insurance will actually do.
ICC (C) covers only major casualties such as fire, collision, or vessel loss. ICC (B) adds named perils like water entry and some dropping during loading. ICC (A) covers accidental physical loss or damage except for listed exclusions. For a machine with servo drives and an industrial PC, only (A) makes sense.
Some buyers tell me a standard all-risk policy is enough on its own. For a professionally crated machine on a conventional route, that view is partly right. But the policy only responds if the five checks above are satisfied. Incoterms 2020 also matter here. Under CIF, we arrange insurance, but you should still read the actual wording, not just the certificate.
Every quote we prepare forces a trade-off: insure at invoice value 3 and keep the premium low, or insure at replacement value and pay more. I push buyers toward the second.
Insure a new pipe cutting machine at replacement cost, not invoice or depreciated value. Add freight, export crating, duties, removal of the damaged unit, reinstallation, calibration, and expedited replacement freight. CIF plus 10% is usually too low. Then check the deductible, often 1% of insured value.

Valuation disputes are the most common claim problem I see after packaging disputes. The insurer and the buyer often mean different things by “value.” Fix that before the machine leaves the factory.
Actual cash value deducts depreciation. For a brand-new machine, that makes no sense, but some policies apply it anyway unless you specify otherwise. Replacement value coverage pays what it costs to put an equivalent machine on your floor. For used or refurbished equipment, insurers often insist on depreciated value 4 and may add special clauses. Ask which basis applies to your shipment in writing.
The numbers below are an illustration, not a quote. They show how the gap opens up.
| Cost item | Illustrative amount | Covered by CIF plus 10%? |
|---|---|---|
| Machine purchase price | $150,000 | Yes |
| Ocean freight and insurance premium | $6,000 | Yes |
| ISPM-15 export crating and bracing | $2,000 | Only if included in CIF |
| Import duties and taxes (where insurable) | $7,500 | No |
| Removal and disposal of damaged unit | $1,500 | No |
| Engineering, reinstallation, and calibration | $8,000 | No |
| Expedited air freight for replacement parts | $5,000 | No |
| Realistic insured value | $180,000 | CIF plus 10% gives only $171,600 |
In this example, CIF plus 10% leaves you about $8,400 short before any deductible. On a custom machine that needs new tooling, the gap grows.
Machinery programs often carry a deductible of 1% of insured value with a minimum dollar amount. On a $200,000 machine that is $2,000. A crushed frame clears that threshold easily. A $1,500 repair to a damaged HMI does not. Ask whether the deductible applies per occurrence or per shipment, and whether partial losses are settled by repair, component replacement, or cash.
Even a perfect valuation covers only physical loss or damage. It does not cover the lead-time gap. A custom-built replacement can take 6 to 12 months, and lost contracts during that period are a consequential loss that basic cargo insurance excludes. Some buyers ask me to push one policy to cover everything. I resist that. A layered approach works better: cargo insurance for transit, warranty for defects, installation-all-risk for commissioning, and business interruption cover for lost production.
I learned the hard way that “all-risk” is a label, not a promise. One crate of ours had a cracked servo drive, no dents outside, and a denied claim.
Standard policies commonly exclude improper packaging, inherent vice, mechanical or electrical failure without external damage, loss of calibration, delay, consequential loss, wear, pre-existing defects, war, strikes, and cyber events. Coverage also usually ends at delivery, before installation and commissioning reveal hidden damage.

That servo drive case taught our team to treat packaging as a coverage issue. Below is the exclusion list I now review with every buyer, and what we do to close each gap.
| Exclusion | How it hits a pipe cutting machine | How we close the gap |
|---|---|---|
| Improper packaging or non-ISPM-15 crating | Claim rejected even under comprehensive cover | Purpose-built crate, documented bracing, photos at every stage |
| Inherent vice and mechanical derangement | Failed controller with no external impact treated as internal defect | Shock and tilt indicators, pre-shipment test records |
| Loss of calibration | Machine looks intact but cutting accuracy drifts | Lock the linear rail and gantry, record alignment before crating |
| Delay and consequential loss | 6 to 12 month lead-time gap, lost contracts | Separate business interruption cover |
| War, strikes, riots, civil commotion | Route through unstable ports or labor disputes | War and strikes endorsements |
| Cyber events | Corrupted PLC software or firmware | Cyber-physical transit rider, offline backup of parameter files |
| End of transit at delivery | Hidden damage found during commissioning | Installation-all-risk policy |
| Used machinery clauses | Depreciated settlement, restricted cover | Agreed value stated in the policy |
Machinery crating and rigging decide whether a claim lives or dies. Our workshop immobilizes the hydraulic cylinder, blocks the cutting head, and seals the electrical cabinet with moisture protection before the crate closes. The center of gravity and lifting points are marked on the outside. We also fit shock and tilt indicators. Modern all-risk policies for automated equipment increasingly treat IoT impact sensors as a condition for payout on high-precision claims, so the sensor data becomes evidence, not decoration.
| Damage found | Likely route |
|---|---|
| Visible impact damage, crushed cabinet | Cargo claim |
| Misalignment after a dropped crate | Cargo claim |
| Faulty controller, no impact evidence | Possibly warranty |
| Incorrect factory assembly | Warranty |
| Corrosion from poor transit protection | Depends on packaging compliance |
| Damage from poor installation | Often excluded from both |
Keep both routes open. Do not start repairs that destroy evidence.
Heavy equipment logistics do not stop at the loading dock. Transit cover often ends at delivery or at a fixed number of days after discharge. But alignment errors in a pipe cutting machine show up during the first production run, not at the door. Ask whether unloading, in-plant movement, installation, and commissioning are covered. If not, add an installation-all-risk policy.
Some logistics professionals argue that prevention beats insurance. I agree in part. Good crating, route planning, and qualified rigging reduce damage. But prevention does not replace insurance. It decides whether the insurance will respond.
Before every pipe cutting machine leaves our Wenzhou workshop, our QC team photographs it bare, braced, crated, and loaded. Those four photo sets win more claims than any policy clause.
Inspect the crate before signing, note every defect on the bill of lading, photograph everything, and notify the carrier, broker, and insurer within the policy deadline. Preserve all packaging, request a surveyor, avoid unauthorized repairs, and submit invoices, packing lists, photos, and the survey report together.

The freight claim process rewards discipline and punishes delay. Most denied claims I have seen failed on paperwork, not on the facts. Follow the steps in order.
A complete transit damage inspection file includes the commercial invoice, packing list, bill of lading, insurance certificate and policy wording, our pre-shipment photos, your receiving photos, the delivery note with damage noted, the survey report, a repair or replacement estimate, and the sensor logs if indicators were fitted. We keep serial numbers and factory test records for every unit so buyers can prove the condition at departure.
Incoterms 2020 decide who holds the risk at each stage, but the insured party and the loss payee decide who can claim. Under CIF we arrange the cover, yet you should be named as beneficiary. Check which country’s law governs the policy and whether claims are paid in your currency. If the bill of lading shows the forwarder as consignee, confirm in writing that claim rights pass to you.
A crushed crate can stop production for months. Shipping insurance coverage is sufficient only when you verify amount, scope, route, exclusions, and claim terms yourself. Email [email protected] for help.
Interested in sourcing the products mentioned in this article? See details and request a quote here:
